Compute Chips

Liquid Cooling Transitions from Optional to Mandatory, Supply Chain Demand Surges
For years, liquid cooling sat on the fringe of mainstream data center design: a powerful but complex option reserved for the most extreme high‑performance systems. Today, that status is changing. As AI accelerators, dense GPUs, and specialized compute ASICs drive rack power far beyond traditional envelopes, liquid cooling is making a decisive transition from “nice to have” to “mandatory” in a growing share of deployments.

Long-Term Replacement Threat of Quantum Computing to AI Chips: Timing and Path
Every major technology wave eventually faces the question of succession: what comes after it, and when? AI chips—GPUs, TPUs, custom accelerators—have defined the current era of machine intelligence by enabling massive parallel computation on classical hardware. Quantum computing, with its radically different model of information processing, is often cast as a long‑term replacement threat to these AI chips. The reality is more nuanced.
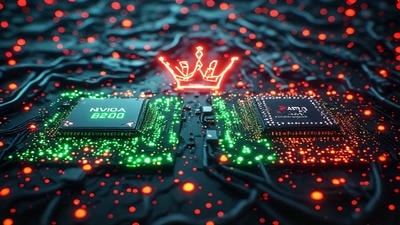
Nvidia B200 vs. AMD MI400: The 2026 AI Chip Crown Battle
By 2026, the race to power large‑scale artificial intelligence has crystallized into a few headline contests, and one of the most closely watched is the emerging battle between Nvidia’s B200 platform and AMD’s MI400 series. Both families target the same high‑stakes arena: training and inference for frontier‑scale models, hyperscale data centers, and enterprise AI deployments that push compute, memory, and networking to their limits.

2026 Changes in Government AI Chip Procurement Lists: Enhanced Security & Trust Requirements
By 2026, government procurement and approval processes for AI chips have shifted from a narrow focus on performance and basic compliance to a broader, more demanding emphasis on security, trust, and lifecycle assurance. Procedure lists that once concentrated on technical specifications, testing protocols, and documentation now embed deeper requirements around supply chain transparency, hardware security features, and verifiable trustworthiness of both silicon and software.

Thermal Simulation Challenges and Solutions in 3DIC AI Chip Design
As AI workloads push chips to deliver ever higher compute density, designers are increasingly turning to three‑dimensional integration (3DIC) to stack dies vertically and pack more functionality into limited footprints. While 3DIC architectures unlock significant performance and bandwidth advantages, they also introduce complex thermal behaviors that are far harder to predict and manage than in traditional 2D layouts.

Commercialization Progress of Neuromorphic Chips: 2026 Application Scenario Validation
Neuromorphic chips have occupied a fascinating space in the semiconductor and AI worlds for more than a decade: rich in promise, modest in revenue, and frequently described as “five years away” from mainstream adoption. By 2026, however, the conversation has shifted. While neuromorphic hardware is still far from displacing GPUs or general‑purpose accelerators, we now see concrete application scenarios where these chips are moving out of labs and pilot projects and into commercial trials, edge products, and specialized services.

2026 AI Chip ASP Trends: Price Pressure Testing After Supply Ramp-Up
Average selling prices (ASP) of AI chips surged through the early waves of the generative AI boom, driven by scarcity, steep performance requirements, and aggressive infrastructure build‑outs. As we move through 2026, however, the story shifts: supply has ramped up across leading‑edge nodes, packaging, and memory, and the market has entered a phase where price pressure is actively testing just how resilient those elevated ASPs really are.
Training Chip Growth Slows, Inference Chips Take the Growth Baton
For several years, AI infrastructure investment has been dominated by a single narrative: build ever‑larger clusters of training accelerators to push the frontier of model size and capability. Capital poured into high‑end GPUs and specialized training chips, and the industry’s growth story revolved around headline figures for compute‑days and parameter counts. Now the center of gravity is starting to shift.

Edge AI NPU Penetration in AI PCs and Smartphones Exceeds 40%
As edge artificial intelligence has shifted from novelty to necessity, one metric captures the depth of that change: neural processing unit (NPU) penetration in client devices. When more than 40% of newly shipped AI PCs and smartphones include dedicated NPUs, it signals a structural transition in how compute is architected at the edge.
Investment Insights from Hot Chips 2026 on the 2027 AI Chip Technology Roadmap
By mid‑2026, the AI hardware world has learned to treat Hot Chips not just as a technical conference, but as an unofficial preview of the next year’s capital flows. Architectures unveiled, packaging roadmaps hinted at, and memory strategies debated on stage all feed into how investors think about the 2027 AI chip landscape. When engineers share their plans, markets quietly rearrange expectations.